Games Workshop’s stock slide raises an awkward Warhammer question: is GW actually selling more, or are hobbyists simply paying more?
Sure, they just posted another record year, so why are investors getting twitchy, and what is with the Games Workshop market value drop? The headline numbers look great, but investors’re asking what’s behind them now, as shares have slid from a £219.40 close on June 26 to around £165 this week.
The Financial Times even asked whether Warhammer is still winning on its Alphaville blog recently after this mystery Games Workshop report, which we reviewed as well, and honestly, after reading it, we kept coming back to questions we have been asking here for years. Prices keep going up, independent stores carry more and more of the load, and getting GW to explain much of anything about it is the real challenge.
We’ve covered Games Workshop stock share price trouble before, including the fan revolt that hit GW’s stock, and we’re hardly calling GW doomed; the company clearly still prints money. But when the financial press starts asking the same questions as online commenters, store owners, and even us, we should all listen.
The FT Just Asked What Store Owners Have Been Asking For Years
Updated on October 25th, 2026, by Rob Baer with the latest thoughts about the Games Workshop market value drop.
- What’s happening: there was a Games Workshop market value drop of about 24.5% from its June 26 peak, even after record FY26 revenue and profit, and the FT is now openly asking whether growth is slowing.
- What we have seen so far: Sales per GW store and per trade account look to have turned negative, a big chunk of trade growth came from about 1,000 new store accounts, and new Armageddon boxes are selling on eBay well under the 15% discount floor.
- What’s next: GW’s half-year results, expected around January 12, 2027, should show whether this is six rough months or the start of a trend.
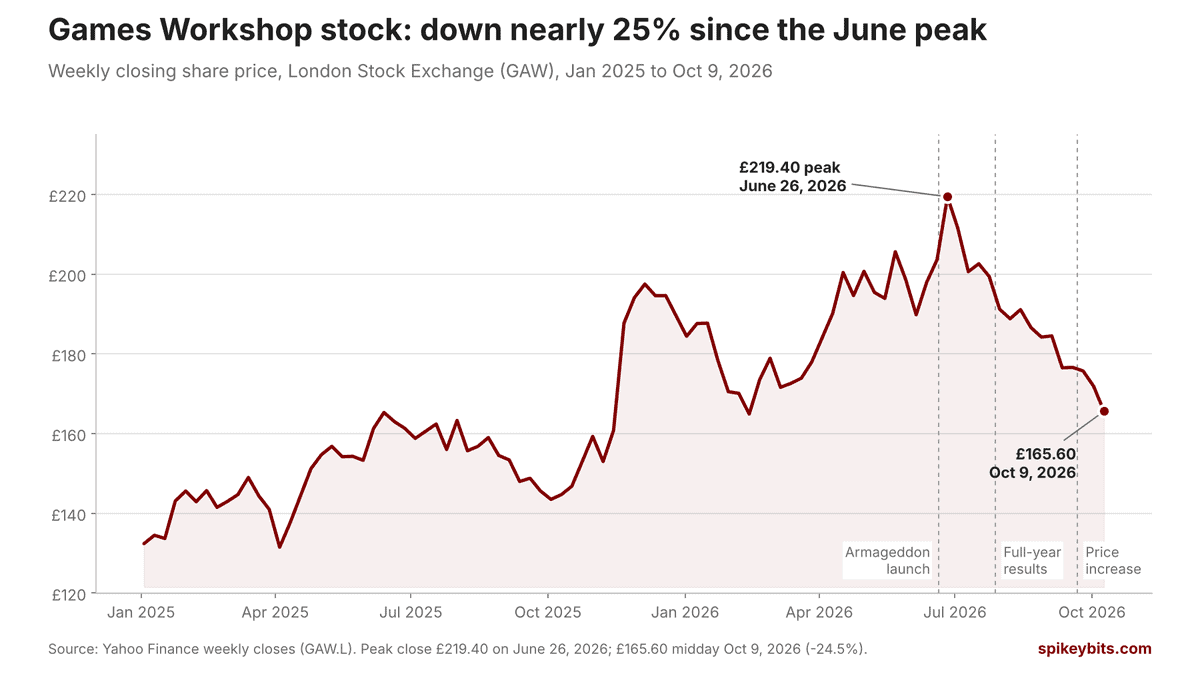
FT writer Bryce Elder points out that GW’s price-to-earnings multiple has come down by about 10 turns. Even after the drop, though, you’re still looking at roughly 27 times earnings. The FT reckons that’s pricey and points out the growth forecasts propping it up come from just three analysts: Peel Hunt (GW’s own broker), Jefferies, and Edison.
The store numbers are what caught our eye, though. According to the end-of-year report, sales growth per GW-owned store went negative in the second half of the 2025-26 financial year. That hasn’t happened since the pandemic, and online sales didn’t make up the difference.
Over on the independent store (trade accounts) side, revenue per trade account looks to have gone negative in the latest period too, and those shops now account for 65% of GW’s sales. With both sides bringing in less per store, something else has to be keeping the overall number growing.
So where’s the Games Workshop market value drop coming from?
Games Workshop Stock’s Record Numbers Can Still Hide a Growth Problem
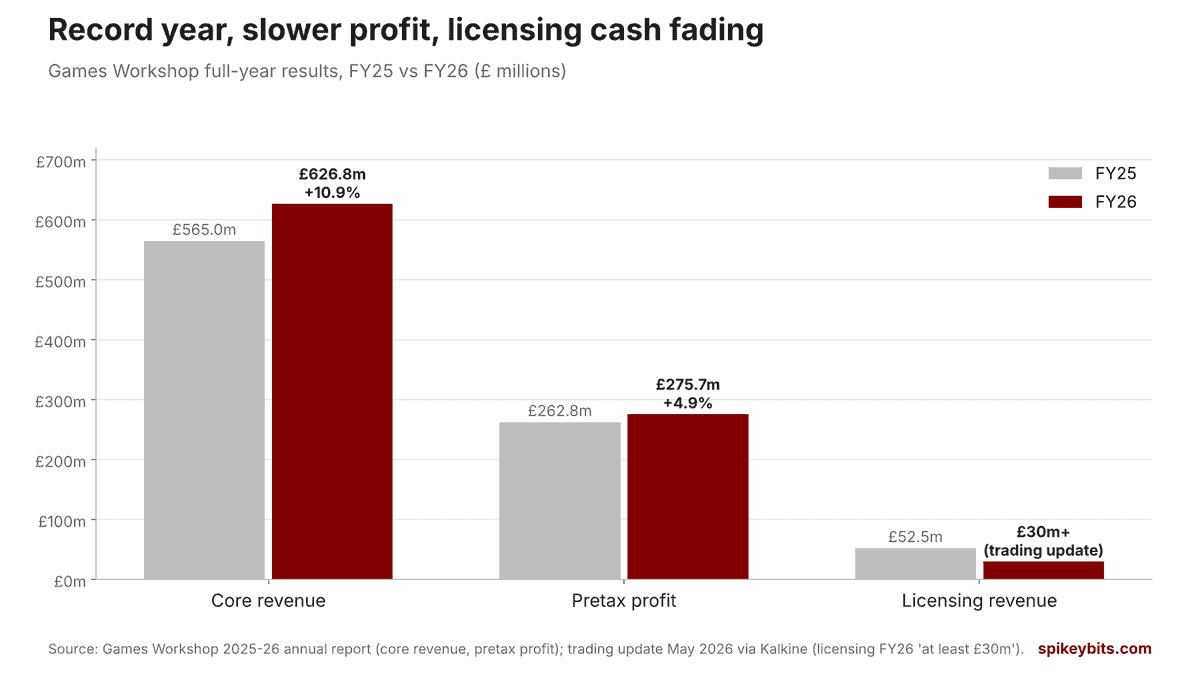
Giving GW credit where it’s due, the annual report shows core revenue up 10.9% to £626.8 million and pretax profit up 4.9% to £275.7 million. That’s plenty of money coming in.
Licensing is going the other way, down from £52.5 million to “at least £30 million” according to GW’s May trading update. Which isn’t unexpected, to be honest, and we covered that slide when GW’s licensing and dividends stumbled at results time.
Then you look at Edison’s FY26 note. Trade revenue grew about 18% in constant currency, but GW also added roughly 1,000 net new trade accounts. That’s about 12% more stores than the year before. Meanwhile, GW’s own retail stores grew about three percent and online store sales grew about two percent.
But both went backward in the UK and Australia/New Zealand, which, while not their biggest countries by volume, are still some of their biggest core consumers.
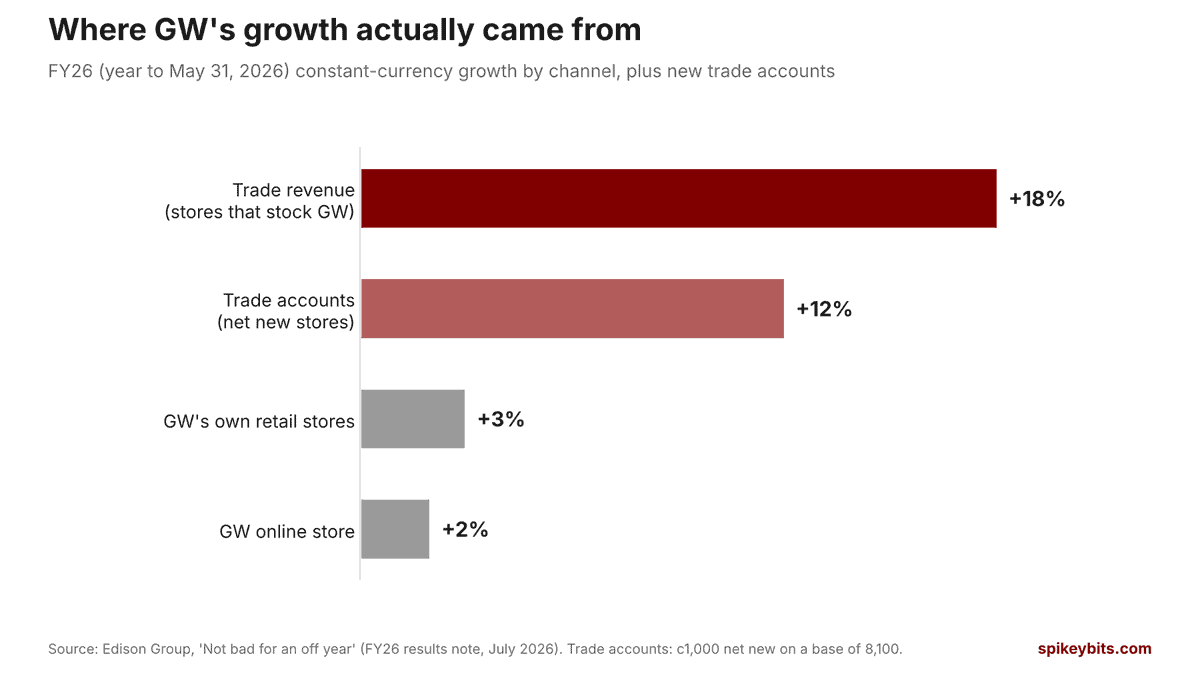
So a lot of that trade growth looks like it came from getting more shops on board, rather than existing shops selling more. That’s our math, not Edison’s, but it also fits what GW’s CEO said in January, when he admitted some of the company’s most established UK and US stores were in like-for-like decline.
Are regular customers coming back for more, or are we looking at opening orders from new accounts plus higher prices on the same boxes? Nobody’s suggesting anything shady with the books, but when you raise prices and sign up 1,000 new accounts to thousands of dollars in “starter packages,” that math can add up fast
We’d just like to know which of those things is doing the most, numbers-wise here.
GW Makes Money, but is the Stock Worth the Price?
The bigger question isn’t whether GW can turn a profit. It clearly can; the question is whether those future profits justify what investors are paying for the shares today.
A traditional retailer wouldn’t normally get this valuation from Wall Street, and neither would a traditional manufacturer. GW does both, but being a bit of each doesn’t automatically make it better at either. The real question is starting to become: how much evidence is there that Games Workshop deserves the extra premium?
Sure the Warhammer IP, the stock’s momentum, and a bit of FOMO can help explain why investors pay more. They don’t settle whether the business underneath is worth that price, though. So, if investors can find more predictable, reliable earnings elsewhere for less, GW needs to give them a reason to pay extra.
On the funding side, GW’s already paying its own way, which is good. Its FY26 annual report says it funds operations entirely from free cash flow.
For the year ended May 31, 2026, GW even brought in £267.7 million in operating cash after tax. After subtracting capital asset spending, product development, and lease principal and interest payments, our calculation leaves about £203.3 million before dividends.
So, there’s also real cash coming out of this business.
And for the roughly £4.5 million raised from issuing shares, the share capital note puts that under the employee sharesave scheme. This means employees are buying shares through the scheme, rather than GW needing a tech-style fundraiser to keep things running.
The company also reports no external borrowing, and it ended the year with £182.9 million in cash and £56 million in lease liabilities. There are leases to pay, but the report doesn’t show a pile of bank loans waiting to get more expensive. So understandably, GW says its interest rate risk isn’t significant.
So overall you have to give GW credit for paying its own bills, but that still doesn’t make its shares a bargain at any price.
Getting Armageddon Into Stores Was the Easy Part
Back in June, we also gave GW credit for the smooth Armageddon launch. The allocations made sense, and there was no exclusive direct-order bait, and we still stand by that. Getting boxes into stores went well, but getting customers to take them home is the other half of the equation too.
And those record annual results can’t tell us how the box is doing, because GW’s financial year ended May 31, three weeks before Armageddon hit shelves on June 20.
The Financial Times called demand “mid at best,” and we agree with what our polls of stores and distributors over the last month or so show as well. At £185, the box costs 23% more than the 10th Edition launch box, and you get fewer models. The older Leviathan box still sells above retail on eBay, while the new one is easy enough to find discounted.
GW charges $295 for Armageddon here. Take off the 15% discount stores are allowed to advertise, and you’re at $250.75 RRP at most stores. We checked secondary-market US sales, and of the 34 new, sealed launch boxes sold on eBay between September 2 and October 8, 28 sold for less than that. The median was $230, and the lowest was $195.50 before shipping. Amazon has it sitting at $250.75.
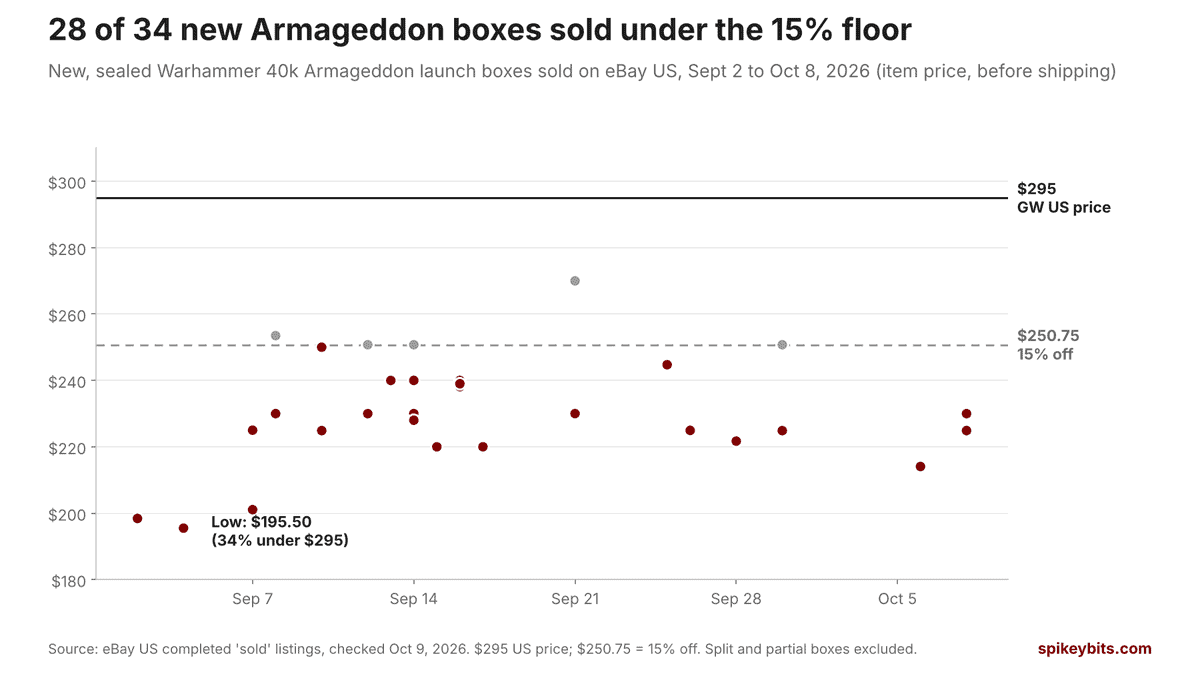
Sealed launch boxes going for more than 20% under MSRP three months after release? That looks like leftover stock because someone ordered more than they could sell, and a shop can’t pay for its next order with cash that’s still tied up in unsold boxes.
Tone Pro is Good Paint With an Awkward Rollout
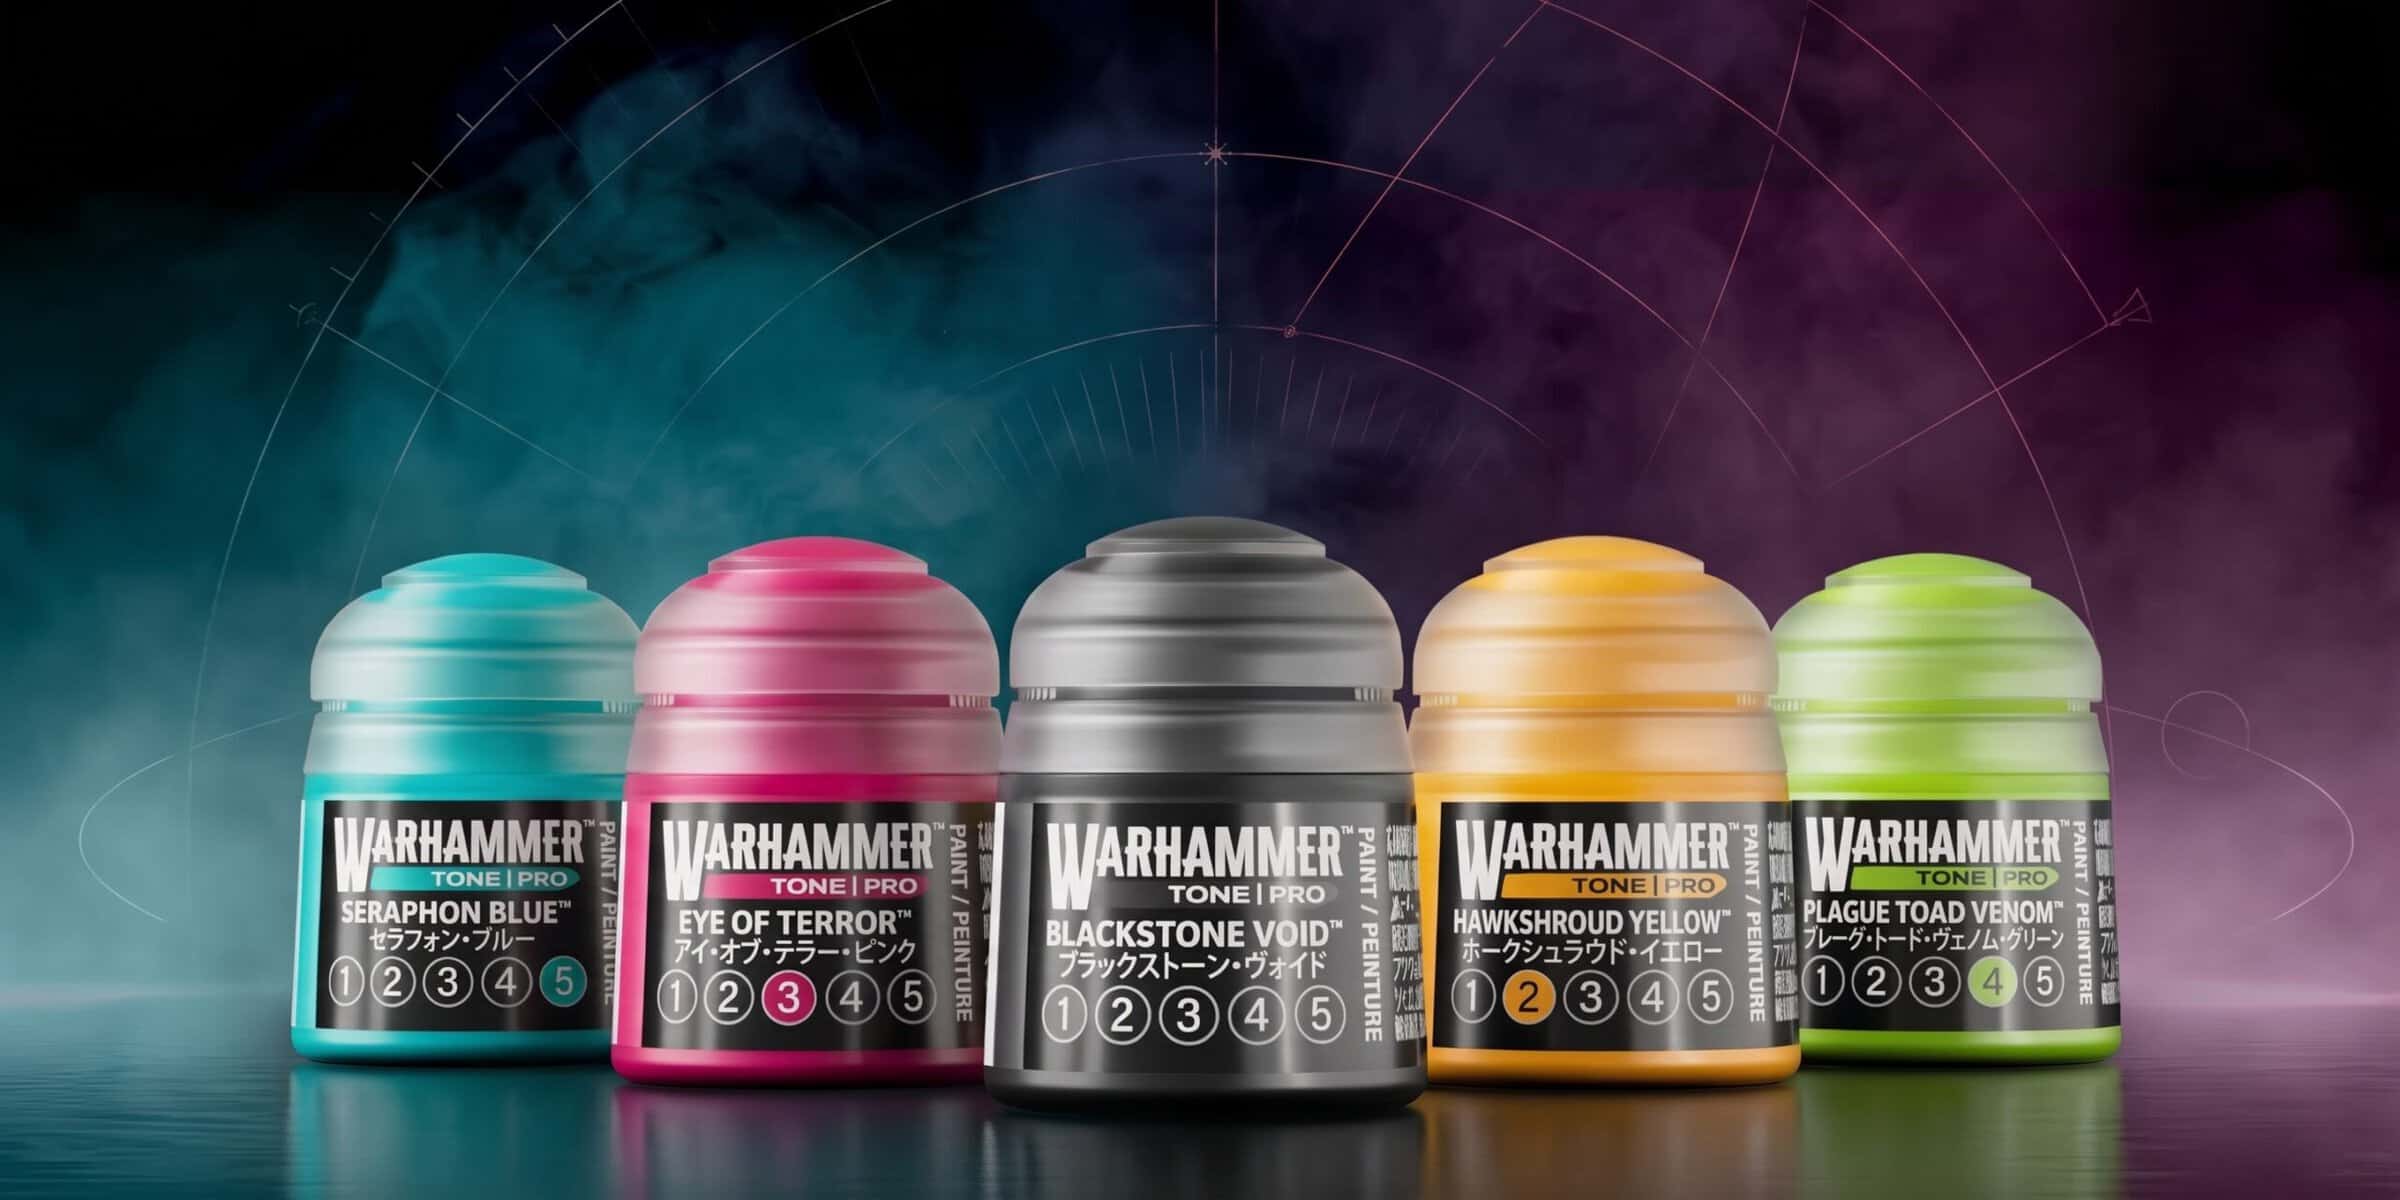
Then there is the Tone Pro issue too,
ICv2 columnist and store owner Scott Thorne says selected full-range paint stockists (the so-called 360 stockist level) got Tone Pro racks forced on them with about three days’ notice, with no one asking them beforehand. And while he expects the paints to sell, as customers are already asking about them, the whole thing seems a little heavy-handed from GW.
So where’s the rack going, and where’s the money coming from to pay for it? Well, that is anyone’s guess, as GW picked the date, but the shops footing the bill have their own buying schedules to work around already this holiday season. They really didn’t need a $3500 bill coming out of nowhere with little notice.
It almost seems like GW could be trying to pull a big “win” out of the financial hat with this, right as their stock is sliding and their retail prices are increasing. Lol, do you see where this is going for their January midyear sales report?
Another thing to consider is that there is plenty of competition in that paint aisle too. Tone Pro’s five numbered tones will be compared with Army Painter’s six-color Flexible Triads. Then you’ve got Monument’s Pro Acryl in 22ml bottles, while the Tone Pro lineup comes in 12ml pots at a whopping $6.75!
We said it looked like Fanatic mixed with Pro Acryl at the reveal, and Tone Pro pricing still runs about twice what those rivals charge.
The FT’s bear case is pretty straightforward: GW has signed up plenty of side-hustle retailers, and if sales flatten, they get stuck with extra stock and stop reordering.
The bear case the Financial Times lays out is pretty straightforward, and we’ve said the same thing with Hyundai dealerships and Antique stores that started carrying Wahammer: GW may have signed up too many retailers who treat Warhammer as a side hustle, while online sellers are using their discount to move normal (and leftover) stock on thin margins.
Once sales flatten these stores get stuck with extra stock, and the growth starts running backward.
GW lists about 9,100 partner stores worldwide, but that’s every account. How many of them are 360 stockists, and actually carry the full paint range, is anyone’s guess, and only GW knows how many of these $3500 racks have been auto-shipped to them.
Higher Prices May Make the Revenue Look Better
We’ve now had two autumn price increases in a row. The 2025 increase took effect October 6, and the 2026 price increases landed September 21 with a 3.9% increase on average this time.
GW has US tariffs to pay too, about £13 million a year according to Reuters. Price increases are part of how it plans to cover that, sure, but charging more brings in more revenue, even if no new hobbyist walks through the door.
Shop’s stocking up before the increase can muddy the picture as well. Because if you know a price increase is coming, you’ll stock up while you can still pay the old price. So then stores place orders that would’ve been normally placed later on over time, and the next few months’ revenue can actually be soft for GW. But that being said, that revenue drop can also potentially be covered up by an increase from holiday sales restocks.
GW’s Silence Leaves Everyone Guessing
As the FT points out, GW doesn’t do results-day conference calls the way most big listed companies do, and its guidance rarely goes past saying trading is in line with the board’s expectations. It mostly leaves the results to do the talking.
That’s easier to live with when everything’s going up, but when the numbers wobble, people would like more of an explanation.
Hobbyists know that feeling, too. Things like the Necromunda RPG got a full reveal, then disappeared from GW’s own preview roundup without a word. Is it canceled? No one knows.
Then there was the Chaos Black Primer recall in South Korea over detected levels of lead. Our focus was on the affected Korean product, not every Citadel spray paint worldwide, but a clear answer on which batches were affected would’ve saved a lot of panic.
And if you’re thinking about your next army purchase, keep in mind there’s ongoing model support to consider now, too. GW just sent 17 Space Marine units to Legends. Put that alongside rising prices and products disappearing without explanation, and you can see why hobbyists might pause before making another big purchase.
Customers have kept buying through every increase, though, so maybe GW should start considering how much it can keep leaning on that loyalty, and what it’s doing to earn the next purchase, instead of just expecting it.
Final Thoughts on Games Workshop Stock Now
Six rough months don’t wipe out decades of GW getting it right, and the Financial Times says as much too. Still, it’s harder to shrug off the complaints about over-commercialization when the per-store figures look like this.
That being said, we’d watch for three things heading into January’s half-year results: revenue per trade account, sales per GW store, and Armageddon’s eBay prices.
Plus, investors have their own reason to pay attention, though now, too. Using Jefferies’ forecasts as an example, they calculate that if GW were valued like a typical retailer with no change to expected profits, the shares would have roughly another 40% to fall.
GW can, however, keep making money and still have shares that cost too much, but in this economy, investors may need an answer to both to stay on board.
(Keep in mind, none of this is investment advice. We just count boxes and talk about toy soldiers.)
🔗 Related Reads:
- News of the GW ‘Fan Revolt’ has Hit Wall Street
- Games Workshop’s Biggest Customers Are Being Treated the Worst
- Games Workshop’s Revenue Stumbles: What’s Next for 40k?
- Looks Like GW Finally Got One Right For Customers and Retailers
- Warhammer Tone Pro Paint Costs Twice as Much as Its Biggest Rivals
- New 2026 Warhammer Price Increases: Complete List Breakdown
Do you think the Games Workshop market value drop is because the hobby is slowing down, or because Games Workshop stock is overvalued and they finally pushed consumer prices too far?